
Apple’s profit-margin outlook and Palantir’s demanding growth expectations have left investors cautious despite strong reported numbers. Our simplified Earnings Mood Score stands at 4/10, highlighting why the market’s reaction matters as much as the earnings themselves.
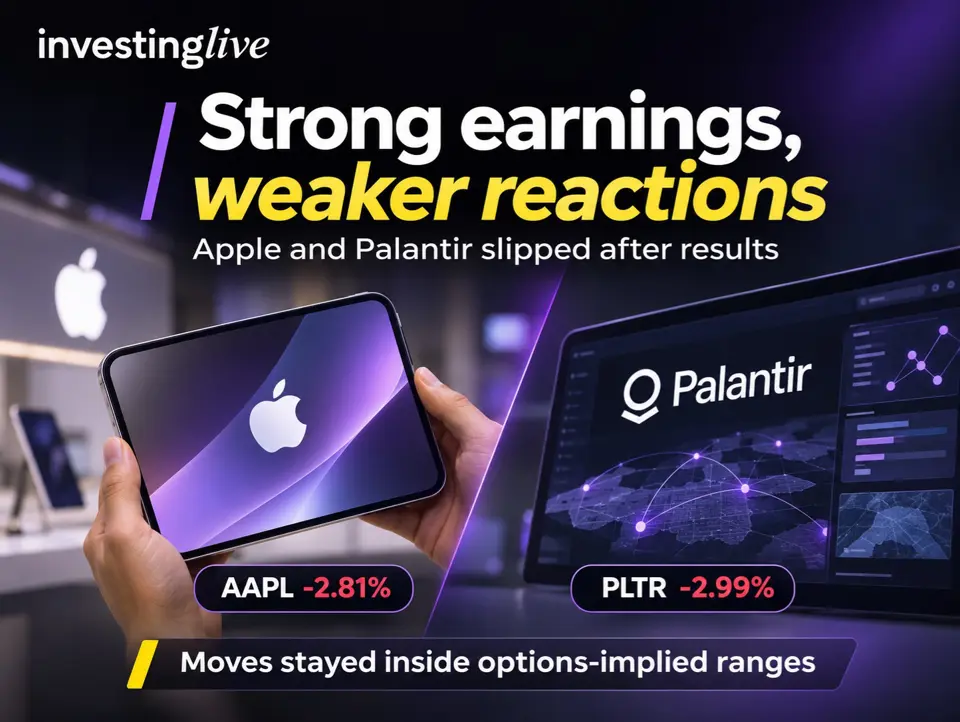
Apple (AAPL) and Palantir (PLTR) delivered stronger-than-expected quarterly results on November 2, yet both stocks moved lower after hours. Neither decline exceeded the options market’s expected move, but the reactions reinforce a broader message from this earnings season: investors remain selective, and impressive numbers alone are not always enough.
That doesn’t mean Wall Street is in panic mode. It does suggest investors are becoming harder to impress, particularly when large companies or popular growth stocks face elevated expectations.
Apple and Palantir: Strong earnings, weaker stock reactions
Apple (AAPL): -2.81% after hours
Apple reported fiscal fourth-quarter revenue of $114.5 billion, up 12% year over year, and earnings per share of $2.10. Both exceeded Wall Street expectations.
However, the company’s outlook introduced a concern. Apple expects gross margins of 45% to 46% for the December quarter, compared with 47.9% in the reported quarter. Rising memory costs are among the pressures on profitability.
Investors appear to be looking beyond strong iPhone sales and asking how much of that growth will translate into future profits.
Palantir (PLTR): -2.99% after hours
Palantir also delivered impressive results. Quarterly revenue increased 96% year over year to approximately $2.31 billion, while the company raised its full-year revenue forecast to roughly $8.53 billion.
Yet its shares initially declined.
Palantir faces particularly demanding expectations because investors are already pricing in substantial growth from artificial intelligence. Reuters also reported a sharp slowdown in growth of U.S. commercial contract value, giving investors another metric to examine alongside the headline revenue beat.
The lesson from both companies is familiar but important: a company can report excellent financial results while its stock delivers a disappointing reaction.
These percentage moves reflect November 2 extended-hours trading, not completed November 3 regular-session returns.
The declines matter, but neither was an unusually large earnings shock
There is an important distinction between the direction of an earnings reaction and its size.
Ahead of the reports, options pricing suggested approximate expected moves of:
-
Apple: ±4.25%
-
Palantir: ±13.32%
Both initial declines remained inside those ranges.
An options-implied move is an estimate of the magnitude of a possible price change, not a prediction of direction or a guaranteed boundary.
Apple’s decline was relatively closer to its expected move. Palantir’s was considerably smaller relative to what options traders had priced in.
That distinction prevents us from mistaking every negative earnings reaction for an unusually severe disappointment.
Earnings Mood Score: 4/10, cautious but not panicking
To make sense of the broader environment, we can look beyond individual earnings headlines and use a simplified Earnings Mood Score, ranging from zero to ten.
Current reading: 4/10
Status: Cautious / defensive
Trend: Slightly worsening
This is a simplified assessment of recent earnings reactions, not a forecast for the S&P 500 or a buy-or-sell signal.
Three indicators help explain the reading.
Breadth: 4/10
Recent completed earnings sessions have shown mixed participation. There are companies receiving positive reactions, but weakness has remained significant enough to keep the overall picture cautious.
Big Names: 3/10
Large, widely followed stocks have been a particular source of concern. Recent reactions involving Alphabet, Intel, Apple and Palantir illustrate the pressure in influential technology and growth names.
Surprise Balance: 4/10
Some downside reactions have proved more consequential than upside surprises. This matters because investors are not merely judging whether companies beat estimates, but also whether their share prices respond positively and sustain those gains.
The broader message is that the earnings environment remains cautious and selective rather than uniformly bearish.
Why a few big stocks can change the earnings picture
Consider two different ways of looking at earnings reactions.
One gives each reporting company equal importance. The other gives larger companies more influence according to their market capitalization.
These approaches can produce very different impressions of the same earnings season.
A broad group of smaller companies might rise after reporting, yet a handful of extremely large companies could still pull the capitalization-weighted result into negative territory.
Apple is particularly relevant here because of its enormous market value.
The completed earnings-session review through November 2 shows repeated negative or nearly flat capitalization-weighted outcomes, despite occasional improvements in participation.
This is similar to the distinction between the performance of an equal-weighted stock index and a capitalization-weighted one, although the earnings-reaction sample is not itself an index return.
For investors holding S&P 500 or Nasdaq-linked funds, understanding that concentration is particularly useful.
An earlier investingLive analysis of Alphabet’s post-earnings decline explored how large-company earnings disappointments can have consequences well beyond individual shareholders.
What would improve Wall Street’s earnings mood?
A reading of 4/10 is not a reason to assume stocks must decline.
It is a reason to pay closer attention to confirmation.
Signs of improvement
More large-cap companies receiving positive earnings reactions would help. So would stronger participation across smaller reporters, fewer outsized downside surprises and evidence that post-earnings gains are holding.
One useful near-term test is whether Apple and Palantir recover their initial losses during the November 3 regular session.
Signs of further deterioration
Additional large-cap selloffs, failed post-earnings rebounds and weakness spreading beyond technology would strengthen the defensive interpretation.
An increase in downside reactions exceeding options-implied expectations would be another important warning.
Importantly, the score would need to be reassessed as new earnings reactions become completed observations.
The most useful earnings lesson may be what happens after the announcement
Strong financial results and positive stock performance are not the same thing.
A headline earnings beat measures reported numbers against published estimates. The share-price reaction also reflects expectations, forward guidance, valuation, positioning and the broader market environment.
Traders can therefore learn something by examining the initial reaction, comparing its size with what options implied, and then watching whether buyers or sellers defend that move during regular trading.
Investors with longer horizons should also distinguish a disappointing short-term reaction from a meaningful deterioration in the company’s business outlook.
For a deeper explanation, see our guide to three important stock earnings lessons for investors and traders.
For now, the Earnings Mood Score remains at 4/10: cautious, defensive and slightly worsening, but far from a universal earnings selloff.
The question for the next reporting sessions is whether major companies can start lifting the mood, rather than merely avoiding disappointment.
Data context: Completed earnings reactions through November 2, 2026, supplemented by provisional November 2 after-hours reactions ahead of the November 3 U.S. regular session. Educational financial news from investingLive. Not investment advice.
What else did I recently find notable for traders and investors?
As central bank policy and equity markets collide, global indices are reacting sharply to shifting macroeconomic signals. Following the Reserve Bank of Australia’s 25bp rate hike as widely expected, broader risk sentiment has faced immediate pressure.
In US equities, Nasdaq indices have given up their gains and trade in negative territory, compounding concerns sparked by the Nasdaq’s worst month since March 2025 which puts returns on AI spending in focus according to BlackRock.
Meanwhile, as earnings growth projections moderate, Goldman Sachs advises investors that you shouldn’t try to time the S&P 500 top as EPS growth is seen slowing to 11%.


